You don’t need to miss payments to damage your credit score. Credit scoring is sensitive to timing, account behavior, and how accurately information lands across credit bureaus. If you’re a student, early in your career, or preparing for a major loan, the difference between “good intentions” and “good credit outcomes” often comes down to a few preventable mistakes—plus a simple set of habits you can start today.
1. First, understand how “good behavior” can still lower your score
Many people assume their score stays stable as long as they pay bills on time. In reality, credit scores can dip when lenders and credit bureaus see new or changing activity. That means certain actions—like closing accounts right before applying for a loan, moving balances between cards, or paying off certain debts at the wrong time—can temporarily hurt your score even if you’re trying to do the right thing.
2. Make smart timing choices around major debt events
If you’re planning to apply for a mortgage, timing matters for older negative items like collections, judgments, and tax liens. Don’t assume that paying them off before you apply is automatically beneficial. In fact, paying certain older debts before closing can cause them to be treated and scored as new, recent accounts with delinquent activity—leading to a score drop. The practical takeaway: ask your mortgage lender whether those debts should be handled at closing instead of beforehand.
3. Be careful when closing credit card accounts
Closing credit cards can feel like a clean financial reset, but it can backfire at first. When you close an account, your score may temporarily fall because it looks like new and recent credit activity. In some cases, scores can recover over months as the credit profile stabilizes. If your goal is to improve your credit before applying for a loan, close inactive or unnecessary accounts well ahead of time—not right before you submit an application.
4. Keep balances low and avoid “moving debt around”
Credit scores tend to respond strongly to revolving credit utilization and account activity. The guidance here is straightforward: avoid carrying high balances on credit cards. Keeping balances under 30% of your available credit on each card can support stronger scores. For instance, with a $1,000 credit limit, aim to keep the balance below $300.
Just as important: don’t shuffle balances between cards to “manage” interest or rates. Moving balances to new cards (even ones with 0% or low introductory rates) can create new activity on your credit report, which may lower your score. If you can, the better direction is paying the debt down rather than cycling it.
5. Apply for credit only when you genuinely need it
Every new credit application can introduce new credit activity, and that can reduce your score—especially when it’s tied to retail promotions or short-term discounts. Department store offers like “apply to get 10–20% off” can be tempting, but opening a new account for a one-time benefit may hurt your credit profile in the short term.
A related strategy is to build and maintain an effective credit history. Credit bureaus generally view someone with a good credit card history more favorably than someone with no credit cards. And beyond cards, having a mix of installment credit (like certain loans) alongside credit cards and mortgages can support a stronger overall credit picture.
6. Verify reporting across all three credit bureaus
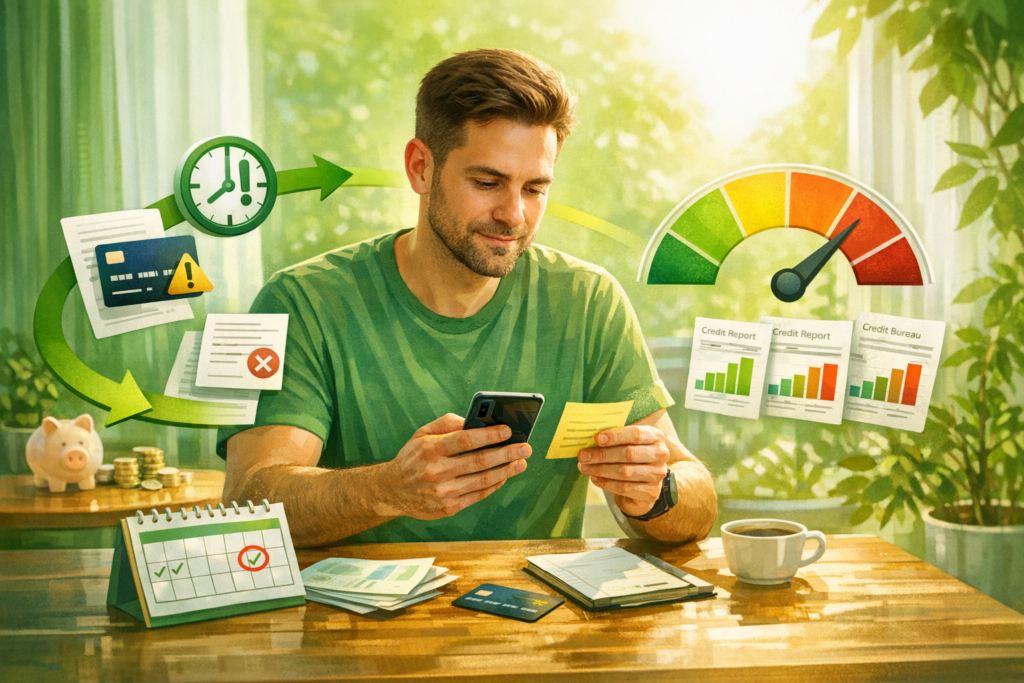
Credit damage sometimes isn’t about your behavior—it’s about whether the bureaus show the correct outcome. Don’t assume that when you pay a collection, judgment, or tax lien, it automatically updates on every bureau. Similarly, when you close an account, assume nothing about whether all three bureaus reflect that change.
Credit reporting can be slow or incomplete, especially when accounts have been sold to collectors. Collection agencies and creditors may not report “paid in full” consistently or promptly. Bankruptcy adds another layer of vigilance: less than half of the accounts, collections, and judgments discharged in a bankruptcy may appear on credit reports after completion. If accuracy matters for your next loan application, you’ll need to confirm that all three bureaus reflect the most recent status—using online disputes or written requests—and support your case with copies of paid receipts and correspondence.
7. Now start building habits in college that won’t sabotage your credit
Credit isn’t only about what you do when you’re preparing for a mortgage—it’s also about how you behave day to day once you have access to credit. If you’re in college, these habits can prevent the common “set yourself back” patterns that lead to higher costs and lower scores later.
Use credit cards only for emergencies, not everyday spending. The money you charge still has to be repaid, and relying on credit for routine expenses can quickly turn into debt you struggle to manage. If you have a card, aim to pay the balance in full every month whenever possible. Carrying a balance often means extra interest costs, and paying on time helps keep debt from spiraling.
Also, pay bills on time. On-time payments help build your credit history, while late payments can trigger late fees and higher interest rates—turning a manageable problem into a more expensive one.
Finally, start saving now. Even if it feels minor in college, early saving builds a habit that supports future stability. It gives you a buffer for emergencies and makes it less likely you’ll lean on credit when you hit unexpected expenses.
If you also need a bank account, shop around for one with minimal fees. Look for no startup fees and no minimum balance requirements, and consider debit card, withdrawal, and deposit fees. Even “small” differences in account costs can add up each year, and lower banking fees help you protect cash flow while you work on credit.
8. The practical goal: reduce surprises in both your credit score and your cash flow
The biggest theme across these credit mistakes is not whether you can make a change—it’s whether the change is timed, measured, and documented. Avoid closing or paying certain debts at moments that can trigger negative scoring effects. Don’t keep high revolving balances. Don’t move debt repeatedly to chase intro rates. Apply for credit only when it’s truly necessary. And confirm that credit bureau reporting reflects the correct status.
If you pair those credit-focused choices with college-friendly money habits—emergency-only credit card use, paying balances monthly, on-time bill payment, early saving, and fee-conscious banking—you give yourself a stronger foundation for future borrowing, not just a higher score in the short term.